The Basket Is Getting Smaller
For years, innovation teams planned around a simple idea: more shoppers, more baskets, more shelf space. GLP-1 medications are putting that idea under pressure.
eMarketer projects that GLP-1-related consumption loss could take 1.1% to 2.7% off grocery revenues in 2026, though much of that spending could be recouped elsewhere. It also expects CPG food volume to fall by 1.4% to 3.4% as consumers switch to smaller package sizes.
That is a planning problem before it is a marketing problem.
What Is Changing on the Shelf
Four signals appear again and again in the trade press.
Smaller packs. Ananda Roy of Circana describes a growing move toward smaller packs and portions, often in resealable packaging, for nutrient-dense foods.
More protein and fibre. Roy says brands are reformulating existing snacks and beverages with less sugar, fat and calories and added protein and fibre, while also launching new products.
Different needs at different stages. Lux Research says there is no single GLP-1 consumer. Before treatment, the focus is weight management and satiety. During treatment, it shifts to muscle preservation, adequate nutrition, digestive support and hydration. Afterwards it is about avoiding weight regain.
Thinner premiums. Roy says the average price premium for new food and drink products has fallen from about 15% to about 6%. Shoppers still want innovation. They are less willing to pay much more for it.
Why Existing Gates Can Miss It
Lux describes GLP-1 as an accelerant of trends already underway, such as functional nutrition and blood sugar management, not a wholly new market. For many companies, it suggests, the fastest response may be to rethink an existing portfolio instead of inventing a new category.
Format becomes part of the product. Lux points out that smaller portions leave less room for a disappointing eating experience, which is why flavour, texture and electrolytes matter. If portion size is only settled late in development, a good concept can still miss.
Claims need care too. Sean Bisceglia of WovenWorks told FoodNavigator that there is no regulation that defines a product as GLP-1 friendly. He advises highlighting attributes such as protein, fibre, caloric density and portion size instead of adding badges. The Hartman Group adds that heavily medicalised positioning could alienate non-users, and recommends reformulation over messaging.
GLP-1 is an accelerant of trends already under way, not a wholly new market.
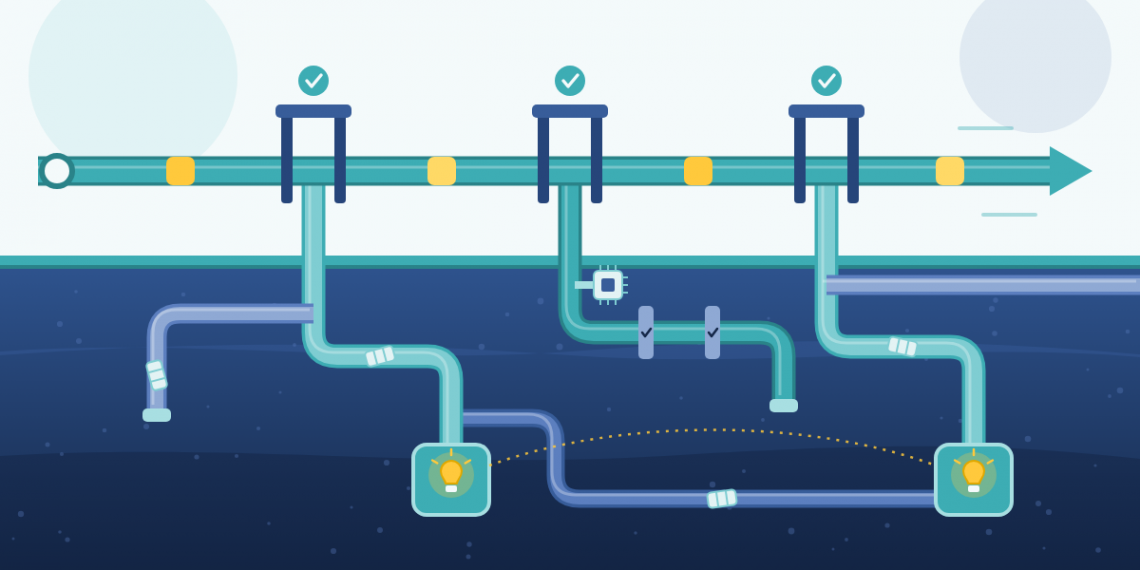
Three Ways to Bring the GLP-1 Consumer Into the Pipeline
1Tag Every Project by Consumer Stage
Use the pre-, active, and post-treatment split, or your own, to state which shopper each concept serves. Gates can then judge fit to a specific need rather than a generic “health” idea.
2Make Format and Claims Gate Criteria
Add portion size and pack format to the concept gate. Give nutrition claims an owner and a review step, so they describe attributes you can stand behind.
3Review the Existing Portfolio First
Before starting new development, list which products could be reformulated, resized or retired, and compare the options on cost and risk.
The Bottom Line
GLP-1 will not rewrite every category, and the size of its effect is still debated. eMarketer expects much of the lost spending could be recouped elsewhere, and Confectionery News notes that questions remain about the overall impact on consumption.
But the signals point the same way: smaller portions, more protein and fibre, and less tolerance for a high premium. Is your team adapting inside the pipeline, or around it?